Your Turning 65 Medicare Enrollment Guide for the Hudson Valley
Reaching age 65 is a major milestone, and Medicare enrollment at 65 comes with a set of rules, deadlines, and decisions that can feel overwhelming fast. At Health Options NY, we have spent 14 years helping people in Saugerties, Kingston, and across the Capital District sort through the alphabet soup of Parts A, B, C, and D, so they can enroll with confidence and avoid the kind of lifelong penalties that catch people off guard. Our services are provided at no cost to you. We are compensated by insurers, not by your premium, which means you get expert guidance without any added expense.
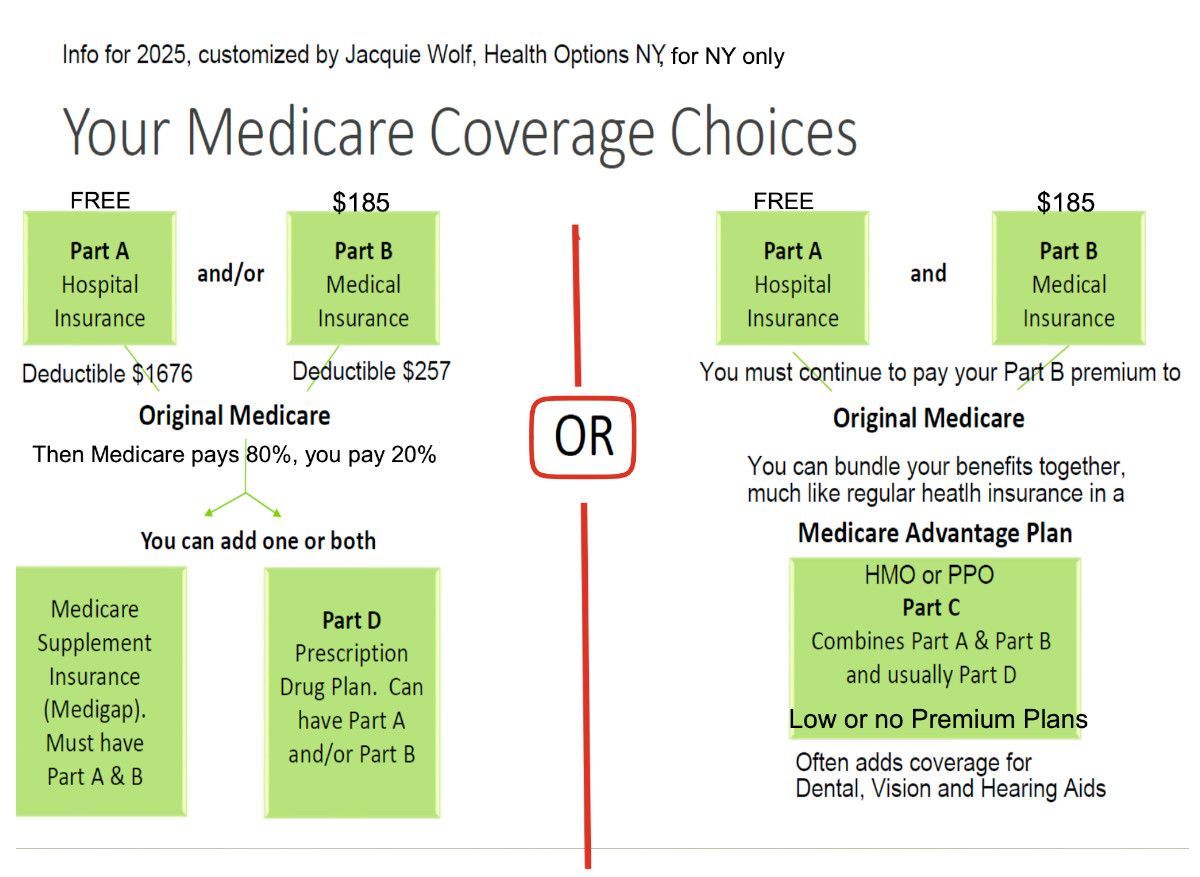
The Medicare enrollment process is not as simple as signing up online and moving on. There are four distinct parts to understand, each covering different aspects of your health care.
- Part A covers inpatient hospital stays, nursing care, and recovery.
- Part B handles outpatient services, medical visits, and preventive screenings.
- Part C, also called Medicare Advantage, bundles many of these benefits through private carriers and often includes dental, vision, and hearing, but comes with network restrictions and plan details that change every year.
- Part D covers prescription drug costs and is also offered through private carriers whose formularies shift annually.
Getting the combination right for your specific situation is where most people run into trouble, and where having an experienced, independent broker makes a real difference.
Many people approaching 65 do not realize that timing your Medicare enrollment incorrectly can have lasting financial consequences. One of the most serious is the HSA tax trap: if you are still contributing to a Health Savings Account and you enroll in Medicare Part A, a 6-month retroactive lookback period kicks in automatically. Any HSA contributions made during that window can trigger tax penalties.
Another major issue is the IRMAA surcharge, which applies to higher-income enrollees. Because IRMAA is calculated on a two-year lag, your 2026 Medicare premiums are based on your 2024 Modified Adjusted Gross Income. If your income has dropped since then due to retirement or reduced hours, you may be able to appeal using Form SSA-44. These are the kinds of details that are easy to miss on your own but straightforward to handle with the right guidance.
Once you understand the basics of when to enroll in Medicare, the next decision is which type of coverage fits your life. Original Medicare (Parts A and B) gives you broad access to providers but leaves gaps in cost-sharing, including deductibles and coinsurance. A Medigap plan, also called a Medicare Supplement, is designed to fill those gaps. In New York, Medigap plans are treated as lifetime contracts with no look-back period, which is a significant advantage. Medicare Advantage (Part C) is a bundled alternative offered through private insurers. It often includes extra benefits but ties you to a specific network.
Our team works with 10 organizations offering more than 20 products, and because we are independent, we are not tied to any single company. That means our recommendations are based entirely on what fits your needs, your budget, and your doctors.
Health Options NY was built on the belief that knowledge is the foundation of every good Medicare decision. That is why we offer Medicare 101 seminars held the 2nd Thursday of every month in Kingston, along with recurring Medicare Mondays workshops for ongoing Q&A. Our Medicare Mastery content is available through our YouTube playlist and LinkedIn newsletter for those who want to learn at their own pace.
Our team includes Jacquie Wolf, who founded the agency 14 years ago; Dr. Eva Turner, a chiropractor with over 30 years of clinical experience who now helps clients in both New York and Florida; and Susan Diamond, a Certified Financial Social Worker with AHIP certification. Together, they bring a depth of medical and financial perspective that is rare in insurance brokerage. Every consultation is personal, unhurried, and focused entirely on you.
When exactly should I sign up for Medicare if I am turning 65?
Your Initial Enrollment Period spans seven months: the three months before your 65th birthday, the month you turn 65, and the three months after. Enrolling during the first three months means your coverage starts on the first day of your birthday month. If you wait until after your birthday month, your start date gets pushed back, which can leave you with a gap in coverage. Missing this window entirely without qualifying for a Special Enrollment Period can result in late enrollment penalties on Part B premiums that last for as long as you have Medicare.Do I still need to sign up for Medicare at 65 if I have employer coverage?
It depends on the size of your employer. If your company has 20 or more employees, your group plan is generally the primary payer and Medicare is secondary, so you may be able to delay Part B without penalty. If your employer has fewer than 20 employees, Medicare typically becomes the primary payer at 65, and delaying enrollment could mean your employer plan pays far less of your bills than you expect. Getting this coordination of benefits question right before your 65th birthday is one of the most important steps you can take to avoid unexpected costs.What is the HSA tax trap and how does it affect Medicare enrollment timing?
When you enroll in Medicare Part A, a 6-month retroactive lookback period is triggered automatically. This means Medicare considers you enrolled going back up to six months before your actual sign-up date. If you made any Health Savings Account contributions during that retroactive window, those contributions are treated as excess and can result in tax penalties from the IRS. To avoid this, you need to stop contributing to your HSA at least six months before you plan to enroll in Medicare Part A. This is one of the more technical timing issues that catches people off guard, especially those who are still working at 65.What is the difference between Medicare Advantage and a Medigap supplement plan?
Medicare Advantage (Part C) is an all-in-one alternative to Original Medicare offered through private insurers. It often bundles prescription drug coverage and may include dental, vision, and hearing benefits, but it requires you to use a specific network of providers and plan details can change each year. A Medigap plan works alongside Original Medicare and is designed to cover the cost-sharing gaps, like deductibles and coinsurance, that Original Medicare leaves behind. In New York, Medigap plans are lifetime contracts with no look-back period, which provides a level of long-term stability that Medicare Advantage plans do not guarantee.How much does it cost to work with a Medicare broker at Health Options NY?
There is no cost to you for working with Health Options NY. The agency is compensated directly by the insurance carriers, not by your premium. This means you receive personalized, one-on-one guidance through the Medicare enrollment process without paying anything out of pocket for the consultation itself. The no-cost model applies whether you are enrolling for the first time, reviewing your current plan during Open Enrollment, or dealing with a more complex situation like an IRMAA surcharge or a multi-state coverage need.What is IRMAA and could it affect my Medicare premiums?
IRMAA stands for Income-Related Monthly Adjustment Amount. It is a surcharge added to your Medicare Part B and Part D premiums if your income exceeds certain thresholds. The calculation uses a two-year lookback, so your 2026 premiums are based on your 2024 Modified Adjusted Gross Income. For 2026, the surcharge begins for individuals with income above $109,000 or joint filers above $218,000. If your income has dropped since that reference year because of retirement or reduced work, you may be eligible to appeal the surcharge using Form SSA-44 through the Social Security Administration.Does Health Options NY serve clients in Florida as well as New York?
Yes. Dr. Eva Turner, a licensed agent on the Health Options NY team, is confirmed as serving clients in both New York and Florida. This is particularly relevant for retirees who split time between the two states and need coverage that works across state lines. Medicare Advantage plans are network-based and may not cover out-of-network care in another state, so understanding how your plan handles multi-state living is an important part of the enrollment conversation for anyone with a Florida connection.What educational resources does Health Options NY offer for people approaching Medicare eligibility?
The agency offers several ways to learn before committing to a plan. Medicare 101 seminars are held on the 2nd Thursday of every month in Kingston, NY, and provide a structured introduction to how Medicare works. Medicare Mondays is a recurring workshop format that allows for ongoing questions and discussion. For self-paced learning, the Medicare Mastery series is available as a YouTube playlist and a LinkedIn newsletter. These resources are designed to give you a solid foundation before your consultation, so the time you spend with an advisor is focused on your specific situation rather than basic definitions.
REVIEWS
At Health Options NY, we simplify Medicare navigation. Our team helps you avoid pitfalls and offers support. If we made your journey easier, please leave a review!
Trusted by the Saugerties Community
Our Saugerties team is committed to making Medicare guidance simple, personal, and easy to understand. If our support has made a difference for you, please consider sharing your experience with a review.
Jacquie Wolf is the best health plan advisor. She knows we ant the best coverage at the most affordable costs. Jacquie feels like a family friend.
- Kathleen Kourie
Health Options NY made selecting the right medicare plan for me and my husband easy. They navigated through all the confusion and answered all our questions and ultimately found the right plan for us.
- Caren Belcastro
Jacquie got on the phone with me and not only helped me sign up for Medicare but, by asking me a series of questions, determined which advantage plans would cover my current physicians and prescriptions.
- Nancy Tierney
Jacquie at Health Options NY has been my go-to health insurance resource and advisor for many years. With her help, knowledge and expertise, navigating this complex and confusing process has become stress-free for me.
- Katie Doty
Ever since I met Jacquie, I knew this was going to be a good thing. Instant connection, with one so knowledgeable, professional, personable, and attentive.
- Rhonda Everett
Eva and Jacquie have been absolutely amazing in helping us navigate private insurance as well as Medicare and supplements. They are both readily available for consultation whenever we have reached out.
- Sue Varrasi