Turning 65 is no small feat — it’s a significant milestone. As we approach our golden years, healthcare assumes a pivotal role in our lives. This is where Medicare comes into play, providing health insurance for those aged 65 or older and those with certain medical conditions. There is a lot to know about Medicare, and navigating the complexities may appear overwhelming. To guide you through this process, we’ve pinpointed eight key facts about Medicare to get you started: Eligibility Criteria To be eligible for Medicare requires being 65 years old, disabled for 24 months, or having End Stage Renal Disease. Coverage Options Medicare is divided into four Parts: A, B, C, and D. Part A covers inpatient care in hospitals and other medical facilities, while Part B covers medical services and supplies, such as doctor visits and preventative care. Part C, also known as Medicare Advantage, combines Part A, and B, and often includes additional benefits such as dental, vision, and hearing. Part D covers prescription drug costs. Private insurance companies provide Medicare Advantage plans and Part D drug coverage. Each part incurs varying costs, including monthly premiums, deductibles, coinsurance, and copays. Enrollment Periods Medicare enrollment is limited to specific times of the year, and it is crucial to enroll during the seven months that surround your 65th birthday. This ensures you can access the benefits when you need them. Failure to do so can result in late enrollment penalties. Additionally, there are special enrollment periods for individuals who continue to work past the age of 65. Late Enrollment Penalties If you miss your initial or special enrollment period, you may face penalties in the form of higher premiums for Part B and potentially Part D coverage as well. It is essential to stay informed about enrollment deadlines to avoid these penalties. Working Past 65? For those who continue to work past the age of 65, it is essential to take proactive steps to ensure coverage upon retirement. Consider options like staying on your employer’s or spouse’s healthcare plan, or signing up for Medicare. Plan ahead to guarantee the right coverage when needed. Medicare Supplement Plans Medicare Supplement plans, which are offered by private insurance companies, help fill the payment gaps left by Medicare. These plans provide coverage for deductibles, coinsurance, and copay costs, albeit with a higher monthly premium. Supplement plans offer peace of mind by reducing out-of-pocket expenses. In- and Out-of-Network Providers: As mentioned earlier, Medicare Advantage (MA) plans, also known as Part C, are provided by private insurance companies. These companies have networks of hospitals, doctors, and healthcare providers that have agreements with the plan. If you’re enrolled in an MA plan, you may be restricted to using providers within this network. Using providers outside the network, except in emergencies, may result in higher out-of-pocket expenses or denial of services. Receiving Medicare through Social Security If you receive Social Security benefits before reaching 65, you will automatically be enrolled in Medicare Parts A and B once you turn 65. A portion of your benefits will go towards covering the Medicare premiums monthly. Premiums and costs for Parts A and B vary based on income level, but most individuals pay the standard premium. If you are not currently receiving Social Security benefits, you must enroll for Medicare through the Social Security Administration website.
Medicare Annual Open Enrollment is a key time for seniors and caregivers. It’s your chance to change your Medicare coverage, making sure it fits your current healthcare needs and budget. This guide will walk you through the essentials of Medicare Open Enrollment, helping you make well-informed choices that best suit your situation. Understanding Open Enrollment Open Enrollment is a designated period each year when Medicare beneficiaries can review and modify their healthcare plans. It runs from October 15 to December 7. During this time, you can: Switch from Original Medicare to a Medicare Advantage plan Switch from an MA plan back to Original Medicare Change to a new Medicare Advantage Plan Sign up for a Part D plan Change to a new Part D plan It’s crucial to take advantage of this window to assess your current Medicare coverage. Circumstances and health needs change over time, so ensuring your plan is still the best fit is essential. By reviewing your coverage, you can identify any gaps or new opportunities for better benefits at a lower cost. Reviewing Current Medicare Coverage Start by considering your current health needs. Has anything changed in the past year? New diagnoses, medications, or treatments can all impact your coverage requirements. Take a moment to evaluate your existing Medicare plans, considering both what they offer and any limitations they may have. If your health conditions or medications have changed, it might be time to reassess your coverage. Plans differ in how they manage specific services and prescriptions, so ensure you’re getting the best possible support for your individual needs. With the right adjustments, you can maintain or even improve your quality of care. Exploring Plan Options Medicare offers a variety of plans, including Original Medicare (Parts A and B), Medicare Advantage (Part C), and Part D for prescription drugs. Each has its own benefits and costs, making it essential to compare them thoroughly. Look at factors like coverage options, network restrictions, and out-of-pocket costs. Health Options NY can be a valuable resource for this process. We will compare different plans based on your specific needs and preferences. By completing a Medicare Review we can help identify which plans best match your requirements. Considering Changes When thinking about switching plans, consider how it might affect your healthcare providers and services. Some plans have network restrictions, which could limit your access to preferred doctors or medical facilities. Additionally, explore plan ratings and reviews to gauge customer satisfaction and service quality. Understanding these elements will help you evaluate the potential impact of changing plans. Consider how a new plan might better serve your current needs or offer additional benefits that weren’t available before. Informed decisions can lead to improved care and lower costs. Financial Considerations Analyzing out-of-pocket costs is crucial when selecting a Medicare plan. Premiums, deductibles, and co-pays can vary significantly between plans, affecting your overall expenditure. Make sure to evaluate your financial situation and how different plans align with your budget. There are resources available for financial assistance if needed. Programs like Extra Help can assist with prescription drug plan costs, while state-specific programs may offer additional support. Knowing these options can ease the financial burden of healthcare. Enrollment Process Enrolling in a new Medicare plan requires careful attention to detail. Gather necessary documentation and information, such as your Medicare card, a list of current medications, and details of any recent healthcare visits. This preparation ensures a smooth enrollment process. Health Options NY assistance is available if you need help navigating enrollment. Medicare helplines, community organizations, and online resources can provide guidance and support. These tools are incredibly valuable for ensuring you make the best choices for your situation. Common Mistakes to Avoid Avoid overlooking changes in coverage details especially for 2025. Every year in September, your Medicare plan issues you a couple of significant documents: The Annual Notice of Change (ANOC) and Evidence of Coverage (EOC). These are probably the most vital documents you receive from your plan annually . Yet, they are often overlooked by most beneficiaries, primarily due to the flood of Medicare-related correspondence in the fall. Don’t take the ANOC and EOC lightly . They provide you with critical information about your plan for the forthcoming year. Your plan delivers these documents to you because , just like any other medical insurance, Medicare plans adjust annually. The ANOC and EOC outline the modifications in your plan for the upcoming year. Potential adjustments can include: Costs: There is usually a shift in your premium, deductible, and co-pays irrespective of the year. Covered services: With a Medicare Advantage plan, the ANOC delineates services that are going to be discontinued next year, as well as those that are being introduced. Provider network: There’s a constant rotation of providers entering and leaving networks each year. Overlooking these documents can lead to you being unaware of your doctor or pharmacy’s exclusion from your plan’s network the following year. Drug formulary: It’s a common routine for Prescription drug plans to amend their formularies. A large number of beneficiaries find out too late that their plan has stopped covering a specific prescription, all because they didn’t go through these yearly notices. Plans can differ significantly from year to year, can terminate , so staying informed is crucial. Verify provider networks to ensure your preferred doctors and facilities are included, and never miss enrollment deadlines—doing so can limit your options. By staying proactive and attentive to these details, you can dodge common pitfalls that might otherwise complicate your healthcare decisions. Final Checklist After enrolling in a new plan, confirm all enrollment details. Keep records of any changes, including documentation of your new plan and any communications you’ve had. This step ensures you have all the information you need should any issues arise. Schedule follow-up appointments or communications with your healthcare providers or insurance broker as needed. This ensures a seamless transition to your new coverage. Additional Tips Staying informed about potential policy changes can greatly influence your Medicare experience. Policy shifts can affect coverage options and costs, so keeping up-to-date is essential. Seek advice from healthcare professionals for insights tailored to your specific needs and circumstances. In summary, Medicare Annual Open Enrollment offers a valuable opportunity to align your healthcare plan with your needs and budget. By carefully reviewing your options and leveraging available resources, you can make informed decisions that improve your healthcare experience. As a consumer, whether in healthcare or any other sector, your goal is to secure the best quality product at the most competitive price . For more guidance, feel free to consult Health Options NY for additional resources and assistance throughout the process.
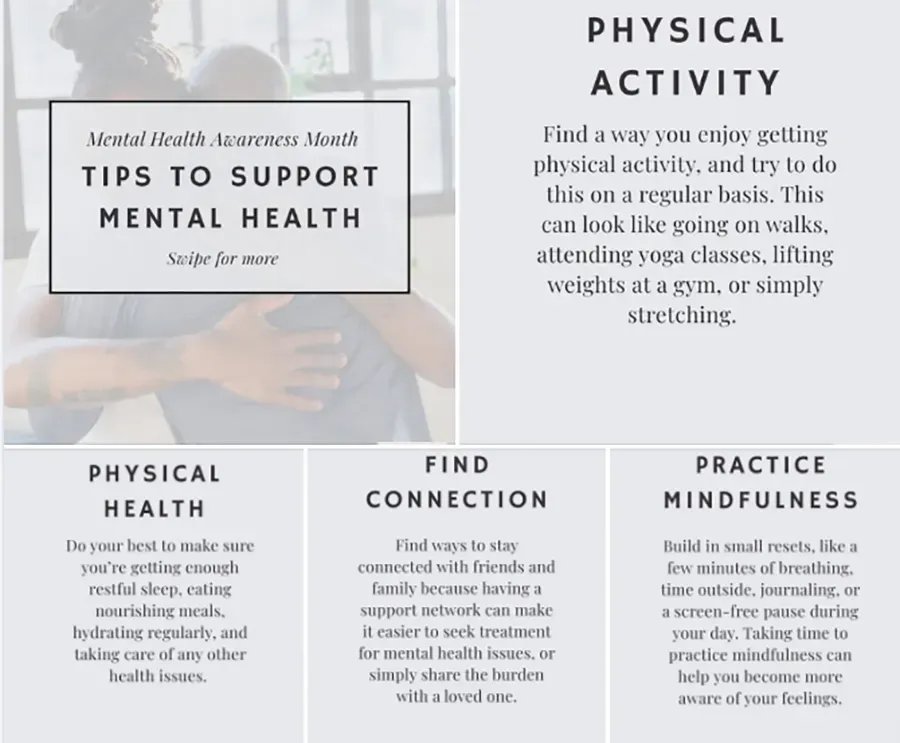
Learn why self-care is vital beyond Medicare. Get practical tips for wellness, nutrition, & stress management today!
Turning 65? Get essential Medicare guidance, enrollment tips, & local support to navigate your options. Contact us for help today!
In this article, we aim to simplify this intricate relationship and equip you with the knowledge you need to make an informed decision
Several of my clients new to Medicare this year weren’t familiar with the Income-Related Monthly Adjustment Amount (IRMAA) and its impact on their Medicare costs. This has prompted me to revisit the topic, especially for those approaching retirement. IRMAA is a surcharge that high-income beneficiaries pay on top of their Medicare Part B and Part D premiums. While starting Medicare is typically a relief, many individuals are surprised by a higher-than-expected first bill due to this surcharge. You will be subject to IRMAA in 2026 if your 2024 income exceeded $109,000 (for an individual) or $218,000 (for a joint tax return). Finding out you owe extra money for Medicare can feel frustrating. Fortunately, you do not always have to accept these higher premiums permanently. If your income recently dropped due to a major life change, you have the right to request a reduction. This guide will explain exactly what IRMAA is, how the government calculates it, and the exact steps you can take to appeal your high-income premiums. Understanding IRMAA and How It Works The Income-Related Monthly Adjustment Amount is a surcharge added to standard Medicare Part B and Part D premiums for high-income earners. The federal government uses this system to ensure that individuals with greater financial resources pay a larger share of their Medicare costs. How the Government Calculates IRMAA To determine if you owe IRMAA, the Social Security Administration looks at your Modified Adjusted Gross Income (MAGI). They calculate your MAGI by taking your Adjusted Gross Income and adding back any tax-exempt interest you earned. The most important thing to understand about IRMAA is the “look-back” period. Social Security uses your tax return from two years prior to determine your current year’s premium. For example, your 2026 Medicare premiums rely entirely on the income you reported on your 2024 tax return. Click the following link to see table for 2026 Medicare premiums, based on your 2024 tax and Medicare costs fact sheet . The Impact on Medicare Part B and Part D IRMAA affects two specific parts of your Medicare coverage: Medicare Part B: This covers medical services, outpatient care, and medical supplies. Everyone pays a standard Part B premium, but IRMAA adds an extra monthly fee on top of that base amount. Medicare Part D: This covers prescription drugs. Even if you purchase a Part D plan through a private insurance company, you pay the IRMAA surcharge directly to Medicare. Because of the two-year look-back period, many new retirees face an unfair situation. You might stop working and experience a massive drop in income. However, Medicare still charges you based on your peak earning years. This is exactly why the appeal process exists. Qualifying Life-Changing Events You cannot appeal your IRMAA surcharge simply because you disagree with the cost. The Social Security Administration requires you to prove that you experienced a specific “Life-Changing Event” that significantly reduced your income. If your income dropped for a reason not on this list, Social Security will likely deny your appeal. The recognized life-changing events include: Work Stoppage or Retirement This is the most common reason people appeal their IRMAA premiums. When you retire, your steady paycheck stops, leading to a drastic reduction in your taxable income. Social Security understands that your two-year-old tax return no longer reflects your current financial reality. Work Reduction You do not have to fully retire to qualify. If you transition to part-time work or significantly reduce your working hours, you can appeal your premium amount. Marriage, Divorce, or Annulment Changes in your marital status often drastically alter your household income. If you get married, divorced, or have your marriage annulled, you can request an adjustment to reflect your new filing status and combined or individual income. Death of a Spouse Losing a spouse is incredibly difficult, and it usually results in a loss of their income stream. Social Security allows widows and widowers to appeal their IRMAA surcharge to account for this sudden financial change. Loss of Income-Producing Property If you lose property that generated income due to a natural disaster, arson, or theft, you qualify for an appeal. You must prove that the loss was outside of your control. Loss of Pension If your pension fund fails or your former employer stops paying your pension, you experience a life-changing event. Employer Settlement Payment Sometimes employers restructure and pay out settlements to employees. If you receive a settlement due to an employer’s closure, bankruptcy, or reorganization, it can temporarily inflate your income and trigger IRMAA. You can appeal once this temporary inflation passes. Step-by-Step Guide to Appealing IRMAA If you experienced one of the life-changing events listed above, you need to take immediate action to lower your premiums. Follow these clear steps to appeal your IRMAA surcharge successfully. Step 1: Gather Your Supporting Documentation Before you fill out any forms, collect the paperwork that proves your situation changed. Social Security requires evidence. Depending on your event, you will need: An original death certificate for a spouse A marriage certificate or divorce decree A letter of resignation or retirement from your employer Pay stubs showing reduced hours Your original tax return from two years ago An amended tax return or an estimate of your new, lower income for the current year Step 2: Complete Form SSA-44 The official document used to request an IRMAA reduction is Form SSA-44, officially titled “Medicare Income-Related Monthly Adjustment Amount – Life-Changing Event. ” You must fill out this form completely and accurately. The form asks you to identify your specific life-changing event and provide an estimate of your modified adjusted gross income for the current year. Be as precise as possible with your financial estimates to avoid underpaying and facing penalties later. Note: If you and your spouse are both enrolled in Medicare Part B, you must each complete a separate appeal form. Step 3: Submit Your Appeal to Social Security Once you have your completed Form SSA-44 and your supporting documents, you need to submit them to the Social Security Administration. You have a few options for submission: Mail: You can mail the physical documents to your local Social Security office. We recommend using certified mail so you have a tracking number and proof of delivery. In-Person: You can schedule an appointment or walk into your local Social Security office to hand-deliver your paperwork. This method often provides peace of mind because you can speak directly with a representative. Fax: Some local offices allow you to fax the documents. Call your local branch first to confirm their preferred method of receipt. Step 4: Wait for a Decision After you submit your appeal, the Social Security Administration will review your case. They will mail you a written decision regarding your IRMAA status. If they approve your appeal, they will adjust your Medicare premiums moving forward. They will also refund any excess premium amounts you already paid for the months following your life-changing event. Helpful Resources for Your IRMAA Appeal Navigating Medicare and Social Security paperwork can feel overwhelming. We compiled a list of direct links to help you manage your appeal process efficiently. Download Form SSA-44: Access the required form and detailed instructions for your appeal right here: Form SSA-44 and detailed instructions . Check Current Medicare Costs: Understand the exact income brackets and corresponding premium surcharges by viewing the most up-to-date data: Medicare Costs and Income Ranges. Locate Your Local Office: Find the mailing address, phone number, and physical location of the nearest Social Security Administration branch: Find a Local Social Security Office . Take Action to Lower Your Premiums Paying more than your fair share for Medicare simply because of a two-year lag in tax reporting puts unnecessary strain on your retirement budget. If you recently retired, lost a spouse, or experienced a major drop in income, you hold the power to fix this issue. Gather your documents, fill out the SSA-44 form, and submit your appeal. The process requires a little bit of administrative work, but the financial savings easily justify the effort. Protect your hard-earned savings and ensure you pay the correct premium amount for your health coverage.
As an HR professional or small business employer, you wear many hats: recruiter, mediator, strategist, and counselor. But one of the most complex roles you play is that of a guide during your employees’ major life transitions. Are you ready for the Medicare Talk? Few transitions are as confusing—or as critical—as the shift to Medicare. When your employees approach age 65, or become eligible for Medicare due to disability, they often turn to you with questions. “Do I have to enroll if I’m still working?” “What happens to my HSA?” *“Which plan pays first?” “Do I need anything besides Medicare?” If you don’t have the answers, the consequences for your employees can be severe. Missing an enrollment window can lead to lifetime late-enrollment penalties. Misunderstanding coordination of benefits can result in rejected claims and significant financial gaps. Why Medicare Literacy Matters for HR Professional Medicare isn’t just a retirement issue; it’s a workforce issue. With more Americans working past the age of 65, the intersection of group health plans and Medicare is becoming a standard part of benefits administration. Your employees are likely receiving a barrage of mail, phone calls, and advertisements about Medicare, much of which is confusing or misleading. By providing clear, objective guidance, you not only protect your employees’ financial well-being but also demonstrate your organization’s commitment to supporting them at every stage of their career. Key Points to Know Here’s what you need to understand: 1. Demystifying the “Alphabet Soup” How to explain Medicare Parts A, B, C, and D in simple, plain language for employees. Provide a primer on what each part covers and how they work together. 2. Critical Enrollment Timelines Did you know that the Initial Enrollment Period (IEP) is a seven-month window? Or that missing it can lock an employee out of coverage until the next General Enrollment Period? Help employees mark their calendars and avoid penalties. 3. The Coordination of Benefits Puzzle One of the most common questions HR gets is, “Who pays first?” The answer depends on the size of your company. < 20 Employees: Medicare is usually primary. 20+ Employees: Your group plan is usually primary. Explaining the nuances of these rules will help employees ensure claims are processed correctly and they aren’t paying unnecessary premiums. 4. The HSA “Tax Trap” This is a critical compliance issue. Employees often don’t realize that enrolling in Medicare Part A (even retroactively) disqualifies them from contributing to a Health Savings Account (HSA). Explaining the 6-month lookback rule will help advise employees on when to stop contributions to avoid tax penalties. 5. Action Steps for HR Professional and Employers Use Analytics: Engage with employees at 64. Develop a Clear Communication Plan: Provide Medicare resources, deadlines, and guidance in your open enrollment and retirement materials. Annual Review: Distribute updated creditable coverage notices. Connect With a Specialist: Partner with a licensed Medicare broker to integrate Medicare into your benefits strategy and answer employee questions. Key Takeaways Educational resources help employees understand Medicare and check eligibility. Informed employees may switch to Medicare for lower costs or better coverage, benefiting both their health and employer costs. Sharing this information empowers employees to make better health and financial choices. Empower Your Workforce Today Navigating healthcare options shouldn’t be a source of stress. With the right tools, you can transform this complex topic into a seamless experience. To help you navigate these conversations with confidence, we’ve designed a handout “ Medicare & Your Employees: Resource Guide” specifically for HR professionals and employers who need quick, accurate, and actionable information.
February is American Heart Month—a timely reminder to prioritize your cardiovascular health. Heart disease is the leading cause of death globally and in the U.S., accounting for nearly one in three domestic deaths. The good news? Many cases are preventable through healthy habits and Medicare’s preventive services. Prevention Through Healthy Habits Daily choices like regular exercise, a nutritious diet, stress management, and quality sleep strengthen your heart. Medicare complements these efforts by offering several key benefits: 1. Screenings and Tests Early detection is vital. Medicare Part B covers cholesterol, triglyceride, and lipid panel tests every five years, plus screenings for high blood pressure and diabetes. Knowing these numbers allows for earlier intervention and better long-term outcomes. 2. Behavioral and Lifestyle Support Medicare covers an annual cardiovascular behavioral therapy session. Your doctor can review your diet and activity levels to provide personalized guidance on reducing risks. 3. Smoking Cessation Smoking is a major cause of heart disease. Medicare Advantage and Original Medicare cover counseling and programs to help you quit. Your heart attack risk drops significantly within just one year of stopping. 4. Cardiac Rehabilitation For those recovering from a heart attack, bypass surgery, or heart valve procedures, Medicare covers supervised exercise and counseling programs designed to strengthen the heart and prevent future events. 5. Hospital Coverage Medicare Part A covers inpatient care for cardiac surgeries and recovery, including rooms, meals, and nursing care. This provides critical financial support during major health events. 6. Annual Wellness Visits Use your annual wellness visit to track indicators like blood pressure and cholesterol. Most plans cover this visit at no extra cost, making it a simple way to stay proactive. 7. Gym Memberships Through Fitness Programs Check if your health insurance provider covering Medicare Medigap or Advantage plans includes the free SilverSneakers, Silver&Fit, or Renew Active programs for unlimited access to fitness locations. Why Preventive Care Matters Combining intentional lifestyle choices with Medicare-covered services helps detect issues early and empowers you to make healthier decisions. These accessible resources make it easier to take charge of your cardiovascular well-being. Final Thoughts Heart disease doesn’t have to be your destiny. This month, schedule your wellness visit and commit to a small change for a stronger heart. By using your Medicare benefits, you can take confident steps toward a healthier future.
Navigating the transition to Medicare can feel complex, especially if you already have health insurance. One of the most important concepts to understand is “creditable coverage.” Knowing whether your current plan qualifies can save you from unexpected penalties down the road. Let’s break down what you need to know. What is Creditable Coverage? Creditable coverage is any health or prescription drug plan that is considered at least as good as what Original Medicare (Part A and Part B) and Medicare Part D (prescription drug coverage) offer. If you have this type of coverage when you first become eligible for Medicare, you can delay your Medicare enrollment without facing late enrollment penalties. Does Your Plan Qualify? Not all health plans are created equal. Here is a quick look at what typically counts as creditable coverage: Employer-Sponsored Plans: Health insurance from a current employer (yours or your spouse’s) with 20 or more employees is usually considered creditable. Union Health Plans: Group coverage provided by a union often qualifies. Veterans Affairs (VA) Coverage: VA benefits are creditable for prescription drug coverage (Part D) but not for medical coverage (Parts A and B). TRICARE: This military health plan is also considered creditable coverage for Part D. What usually does NOT count? COBRA: This is not considered active employment coverage, so you generally must sign up for Medicare when eligible, even if you have COBRA. Small Employer Plans: If the company has fewer than 20 employees , you often need to sign up for Medicare Part A and B when you turn 65, as the employer plan becomes secondary. Retiree Insurance: These plans often require you to have Medicare to work correctly. Why Is This So Important? (The Penalties) This is where creditable coverage becomes crucial. If you don’t enroll in Medicare when you’re first eligible and you don’t have creditable coverage, you could face lifelong penalties when you do sign up. This isn’t a one-time fee. It is added to your monthly premium for as long as you have Medicare. Part B Penalty: For every 12-month period you could have had Part B but didn’t, your monthly premium may go up by 10%. This penalty lasts for as long as you have Part B. Part D Penalty: This is calculated as 1% of the national base beneficiary premium for each month you were eligible but unenrolled. This penalty is also permanent. The Bottom Line: If you don’t have creditable coverage, you need to enroll in Medicare during your Initial Enrollment Period to avoid these extra costs. What to Do If You Lose Creditable Coverage Losing your creditable coverage (for example, if you stop working) triggers a Special Enrollment Period (SEP) . You typically have eight months from the time your employment or coverage ends to enroll in Medicare Parts A and B without penalty. For Part D, the window is shorter, so acting quickly is key. Your Action Plan Check Your Status: Every September, plans are required to mail a “Notice of Creditable Coverage.” Check your mail for this document. If you can’t find it, contact your HR department or benefits administrator immediately. Don’t Assume: Just because you have insurance doesn’t mean it’s creditable. Ask specifically: “Is my coverage creditable for Medicare Part B and Part D?” Keep Your Records: If you delay Medicare enrollment, you will eventually need to prove you had creditable coverage. Keep those notice letters safe! Watch the Clock: If you lose your creditable coverage (e.g., you retire or leave your job), you have an 8-month Special Enrollment Period to sign up for Medicare without penalty. Do not miss this window. Navigating Medicare can be complex, but understanding your coverage status will give you peace of mind and financial security. Making an informed decision now puts you in the driver’s seat for the future.
Medicare beneficiaries will see changes to their premiums and deductibles in 2026. Costs for Medicare Parts A, B, and D are projected to increase. Understanding these upcoming adjustments to your premiums, deductibles, and other out-of-pocket expenses is essential for managing your healthcare budget effectively. The exact amounts you pay will depend on your specific plan choices and income level. It’s also important to be aware of the Income-Related Monthly Adjustment Amount (IRMAA) , a surcharge applied to Part B and Part D premiums for individuals with higher incomes. For high earners, this can add a significant amount to monthly costs, with Part B surcharges ranging from $81.20 to $487.00 and Part D surcharges from $14.50 to $91.00. Each year, Medicare’s open enrollment period runs from October 15 to December 7. This is your annual opportunity to review your coverage. During this time, you can move from Original Medicare to a Medicare Advantage plan, or switch back. You can also select a different Medicare Advantage plan or a new Part D prescription drug plan for the upcoming year. Part A: Hospital Insurance Costs The Medicare Part A deductible for inpatient hospital stays is set to rise to $1,736 in 2026, an increase of $60 from the 2025 figure of $1,676. This deductible covers the beneficiary’s share of costs for the first 60 days of an inpatient hospital admission within a benefit period. A new benefit period begins each time you are admitted to a hospital and haven’t received any inpatient hospital care for 60 consecutive days. Because there is no cap on the number of benefit periods you can have in a year, it’s possible to pay the Part A deductible multiple times annually. For hospital stays that extend beyond 60 days, daily coinsurance payments apply. In 2026, the coinsurance for days 61 through 90 will be $434 per day, which is up $15 from $419 in 2025. For lifetime reserve days (days 91 and beyond), the daily cost increases to $868, a $30 jump from the 2025 amount of $838. If you require care in a skilled nursing facility, the daily coinsurance for days 21 through 100 of extended care will be $217.00 in 2026. This is a $7.50 increase from the 2025 rate of $209.50. It is crucial to remember that Part A does not cover long-term custodial care, which includes assistance with daily activities like bathing and eating. Part B: Medical Insurance Premiums For 2026, the standard monthly premium for Medicare Part B will be $202.90. This represents a nearly 10% increase, or $17.90 more than the $185 premium in 2025. Additionally, the annual deductible for Part B beneficiaries will rise to $283 in 2026, a $26 increase from the 2025 deductible of $257. Part B coverage includes doctor’s appointments, outpatient care, durable medical equipment, home health services, and various preventive services. After you have met your annual deductible, you are typically responsible for 20% of the Medicare-approved amount for most services. This 20% share is known as your coinsurance. Higher Premiums for High Earners (IRMAA) Individuals with higher incomes pay an additional amount for their Part B coverage through the IRMAA surcharge. This amount is determined annually based on your income reported to the IRS. If your income fluctuates from year to year, your IRMAA status could also change. The Social Security Administration (SSA) will notify you if you are required to pay an IRMAA, explaining the new premium amount. This surcharge means that higher-income beneficiaries cover a larger portion of their Part B costs. For 2026, if your 2024 adjusted gross income (AGI) was over $109,000 (for single filers) or $218,000 (for married couples filing jointly), you will pay a surcharge between $81.10 and $486.50 on top of the standard premium. Part D: Prescription Drug Plans If you have a standalone Part D prescription drug plan, you’ll need to check your monthly premium and drug formularies. The same applies if you’re enrolled in a Medicare Advantage plan that includes drug coverage. The maximum annual deductible for Part D plans will be $615 in 2026, which is $25 more than the 2025 deductible of $590. The cap on out-of-pocket drug costs, will be $2,100 in 2026, up slightly from $2,000 in 2025. This cap applies only to medications covered by your specific Part D plan and does not include spending on drugs covered under Part B, such as certain injections administered by a physician. Payment Plan Option Part D enrollees have the option to spread their out-of-pocket costs throughout the year. The Medicare Prescription Payment Plan allows you to pay a set monthly amount instead of facing large, one-time costs at the pharmacy. If you opt into this program through your Part D plan provider, you will be billed monthly for your share of prescription costs. This bill is separate from your regular plan premium. You can directly opt in to the Medicare Prescription Payment Plan through your Part D plan sponsor. IRMAA for Part D Similar to Part B, a surcharge for high earners applies to Part D coverage. If your 2024 AGI exceeds the thresholds of $109,000 (single) or $218,000 (married filing jointly), you will pay an additional amount for your prescription drug plan. This surcharge ranges from $14.50 to $91.00 per month and applies even if your drug coverage is part of a Medicare Advantage plan. Covering the Gaps: Medigap and Medicare Advantage Original Medicare does not cover all healthcare expenses. Part B, for instance, only covers 80% of outpatient services, leaving a 20% gap. Furthermore, services like routine dental, vision, and hearing care are not covered. You have two main options to address these gaps: purchase a Medigap policy or enroll in a Medicare Advantage plan. Medigap (Medicare Supplement Insurance) Private insurance companies sell Medigap policies to help cover out-of-pocket costs like deductibles and copayments that come with Original Medicare. These plans are standardized and labeled with letters A through N. A plan with a specific letter offers the same basic benefits regardless of the insurance company selling it. Medicare Advantage (Part C) A Medicare Advantage plan is an all-in-one alternative to Original Medicare. These plans, sometimes called Part C, are offered by private companies approved by Medicare. If you join an MA plan, you get your Part A and Part B benefits through the plan, and most also include Part D prescription drug coverage. You cannot have both a Medigap policy and a Medicare Advantage plan. MA plans often have lower premiums than Medigap policies but may come with higher deductibles and copayments. They also typically have provider networks, which may limit your choice of doctors and hospitals. Unlike Original Medicare, MA plans have an annual maximum out-of-pocket limit. For 2026, this limit is $9,250 for in-network services and $13,900 for out-of-network services. It’s important to check your plan’s Annual Notice of Change, as some major insurers are reducing their plan offerings in 2026, which could affect your coverage. If you are feeling uncertain about how these changes could impact your coverage or need assistance in choosing the right plan for your needs, Health Options NY is here to help. We can provide personalized guidance and ensure you make informed decisions about your healthcare coverage. For more guidance, CLICK HERE for a FREE consult—don’t leave your healthcare to chance! #Medicare2026 #HealthcareCoverage #HealthOptionsNY #MedicareChanges #HealthcarePlanning #PlanSmart #FreeConsultation #HealthGuidance #MedicareReview #StayInformed #Healthcare #OpenEnrollment